Renovation & Construction Loans in Burbank and Glendale
Bring your vision to life with Renovation and Construction Loans designed for homeowners and buyers in Burbank, Glendale, and across California. Corbett Uzel provides financing options to remodel your current home or build a new one, guiding you through each step so you can create a space that perfectly matches your lifestyle and goals.
Renovation and Construction Loans
What Are Renovation and Construction Loans?
Renovation and construction loans are designed to finance the cost of home improvements, remodeling, or new home construction. These loans allow homeowners and buyers to upgrade, repair, or build properties with structured financing that releases funds in stages as work is completed.
Who Can Benefit from a Renovation or Construction Loan?
These loans are ideal for homebuyers purchasing fixer-uppers, homeowners looking to renovate, and individuals building a custom home. Investors can also use these loans to rehab properties for resale or rental income.
How Do Renovation and Construction Loans Work?
Unlike traditional mortgages, renovation and construction loans provide funding in stages rather than a lump sum. Lenders disburse payments based on project milestones, ensuring that contractors and builders receive payments as work progresses.
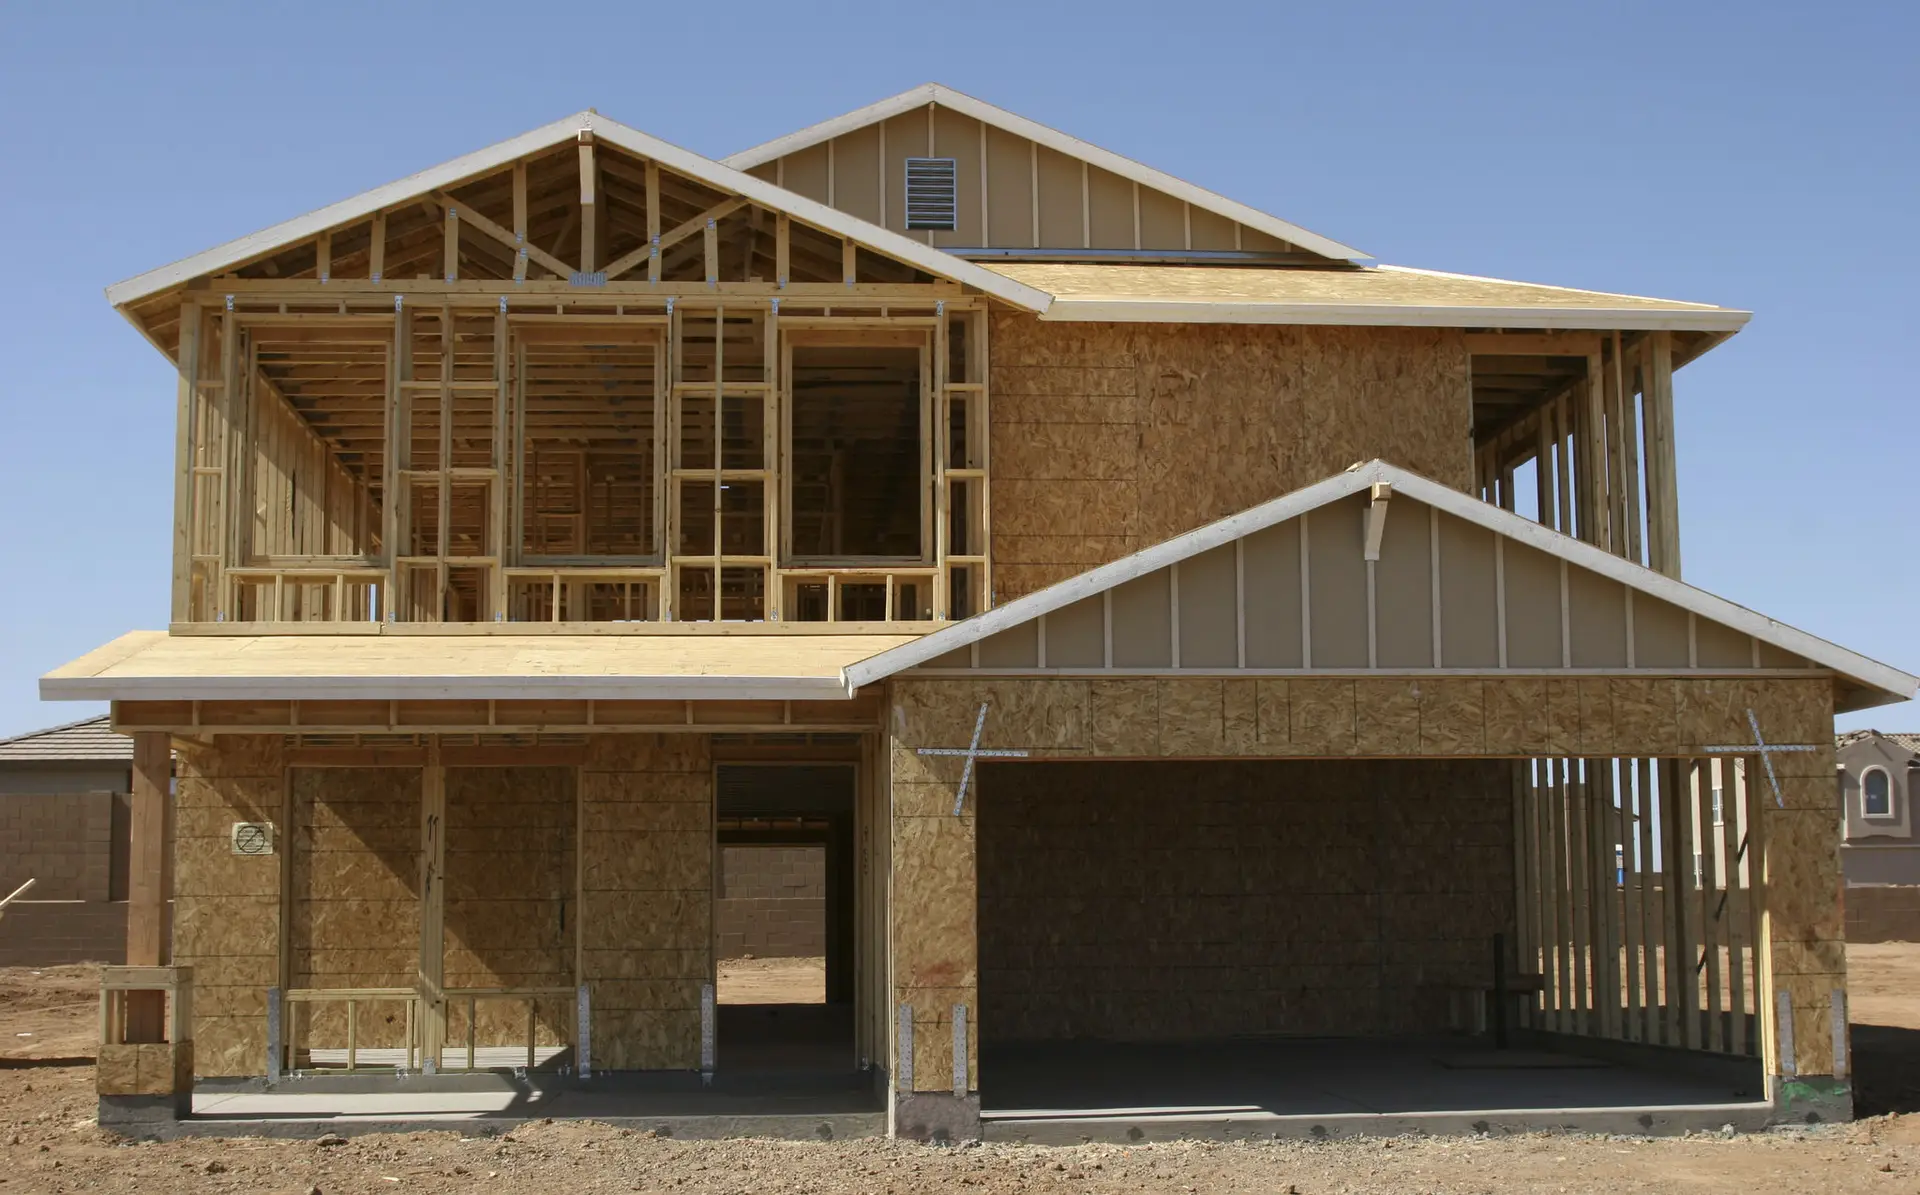
What Types of Renovation and Construction Loans Are Available?
Loan options include FHA 203(k) renovation loans, Fannie Mae HomeStyle loans, VA renovation loans, construction-to-permanent loans, and standalone construction loans. Each loan type has different requirements based on the scope of work, borrower qualifications, and loan terms.
What Are the Benefits of a Renovation or Construction Loan?
These loans provide flexible financing for remodeling, home improvements, or new construction. Borrowers can increase their home’s value, customize their living space, and spread renovation costs over time instead of paying upfront.
Is a Renovation or Construction Loan Right for You?
If you’re looking to upgrade your home, purchase a fixer-upper, or finance a custom-built home, a renovation or construction loan may be the perfect solution. A mortgage specialist can help determine the best loan option for your project.
Why Choose Us for Your Renovation or Construction Loan?
We specialize in renovation and construction loan solutions tailored to homeowners, buyers, and real estate investors. Whether you’re looking to remodel your home, buy a fixer-upper, or build a new property, our loan programs provide flexible financing options, competitive rates, and expert guidance.
From loan application to project completion, our mortgage professionals ensure a smooth financing process, working with trusted lenders and approved contractors to bring your vision to life.
If you’re ready to finance a home renovation or new construction project, contact us today to explore your options and take the next step toward your dream home!
Renovation and construction loan FAQs
A project needs a financing plan as well as a building plan. Corbett can help California borrowers identify the loan questions to resolve before committing to a contractor or closing schedule.
How does renovation financing differ from construction financing?
Renovation financing generally funds improvements to an existing home, sometimes together with a purchase or refinance. Construction financing supports building work and may use staged disbursements. The lender needs to understand the property, scope and intended end use before confirming the appropriate program.
Can one loan cover buying and repairing a fixer-upper?
Some programs combine an eligible purchase and renovation into one mortgage. FHA 203(k) and Fannie Mae HomeStyle Renovation are examples with distinct rules. Program availability and the proposed work must be confirmed; not every property or improvement fits every renovation loan.
What information should I collect about the project?
Prepare the purchase or current-property details, proposed work, contractor estimate, anticipated permits and schedule. Ask which plans, contracts and cost breakdowns the lender requires before paying for a final bid package. A vague remodeling allowance may not be enough for underwriting.
How are renovation funds paid to the contractor?
Disbursement follows the loan’s rules, often through a controlled process tied to completed work and inspections. Ask who approves each payment, what evidence is needed and how delays are handled. Do not assume all renovation funds become unrestricted cash at closing.
Can I do the building work myself?
Only if the specific loan program and lender permit it and all conditions are met. Many arrangements require approved contractors or particular documentation. Confirm this before setting a labor budget; reimbursement for your own work must not be assumed.
What if the project goes over budget?
Ask about required contingency funds, change-order approval and responsibility for overruns before closing. Extra costs may need to be paid from your own funds, and additional borrowing is not automatic. Keep a realistic buffer for unexpected conditions and timing changes.
How does a construction-to-permanent loan work?
It is designed to move from a construction phase into longer-term mortgage financing under the agreed structure. Confirm whether there is one closing or more, when the permanent rate is set, what completion conditions apply and whether finances must be reviewed again. These details vary by product.
Information checked September 7, 2026. Further reading: HUD: rehabilitation financing · Fannie Mae: HomeStyle Renovation.